This morning, Ampol (ALD), Australia’s largest energy distributor and retailer, released its half-year results for 2026, demonstrating the strength of recent refining margins, with first-half profits coming in $42 million above upgraded guidance. This is surely the best result of the season. The HNW Portfolio has a 5% weight to ALD.
Key Points:
- Record Profits: Ampol’s half-year profits increased by +376% to $857 million, driven by a significant increase in earnings from the Lytton Refinery and Ampol’s international trading division. Outside of oil-linked earnings, Ampol increased its retail sales earnings by 12%, with further growth expected in the second half with the inclusion of EG sites.
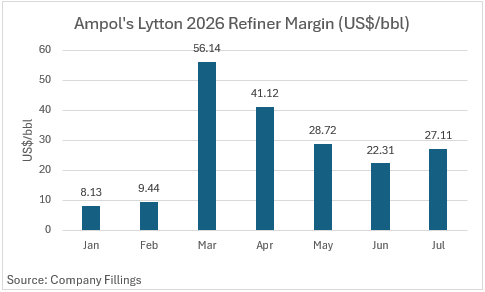
- Lytton Refinery: The Lytton refinery had a stronger half, which saw profits more than 10x to $567 million, driven by an appreciation in refinery margin due to ongoing geopolitical events in the Middle East as well as damage to Russian refineries from Ukrainian drones (See Below). Over the next year, the refinery will undergo an ultra-low sulphides upgrade, which will further increase margins due to lower sulphide content in its fuels.
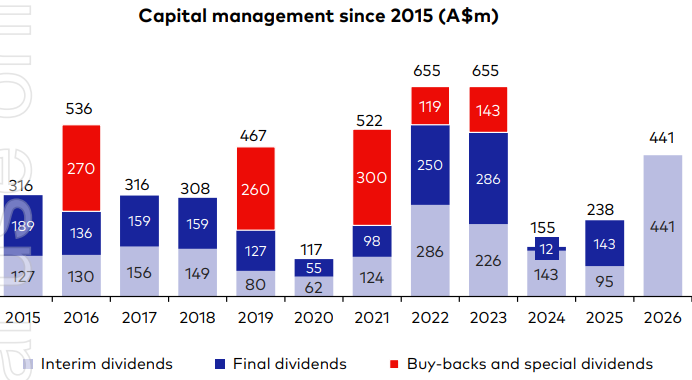
- Balance Sheet: The Ampol balance sheet remains quite strong with net debt of $3.5 billion, post the $1.1 billion EG acquisition, or 1.8x leverage, below the long-term target range of 2-2.5x. The strong balance sheet will likely support further capital returns in the second half with ALD’s franking account balance expanding.
- Record Dividend: ALD announced a fully franked interim dividend of $1.85 per share, representing a lower payout ratio of 51% of profits (target 50-70%). The dividend and payout ratio are expected to increase in the second half as the EG integration progresses and refining margins remain resilient.
- Outlook: Ampol management outlined that they expect EG earnings from the 480 new service stations acquired to begin contributing to profits in the second half of the year, with the refinery operating at only 70% of capacity whilst it undergoes a major maintenance turnaround.
Portfolio Strategy: ALD is the core energy exposure in the Portfolio but with greater exposure to fuel and food retailing rather than the vagaries of the oil price. Over the past five years, ALD has changed from a capital-intensive business with volatile earnings dependent on global refining margins to one increasingly based on fuel and convenience retailing and bringing franchised service stations in-house. ALD trades on an undemanding = 15x forward earnings with a 5% fully franked dividend yield if refining margins retreat to normal levels. At current levels, ALD trades on 8x earnings with a 9% fully franked yield.
While EV penetration is increasing in Australia, in the first half of 2026 this represented 21% of new car sales but only 4% of the passenger fleet. Australian fuel demand has continued to grow, though ALD have made moves to capture revenue from EVs by installing fast chargers at 356 sites across Australasia, charging customers ~$50 to charge a Tesla while selling high-margin cans of Coke and ice blocks.
ALD finished up 4.3% to $41.57 and has been a solid contributor to the portfolio, up 44% over the last 12 months.