This morning, Woodside (WDS) reported its first-half 2026 results with few surprises; they were solid as expected. Overall, a solid result from Australia’s largest energy company with a nice increase in the dividend. The HNW Portfolio holds a 5.5% weight to WDS.
Key Points:
- Profit: Net profits of US$1,334 million, a +7% increase over last year, reflecting a rise in the oil price which offset lower production due to planned maintenance and modifications to Pluto LNG to integrate gas from the offshore Scarborough Energy Project that kicks off later on in 2026. Pleasingly, costs were controlled at $8.8 per barrel of oil.
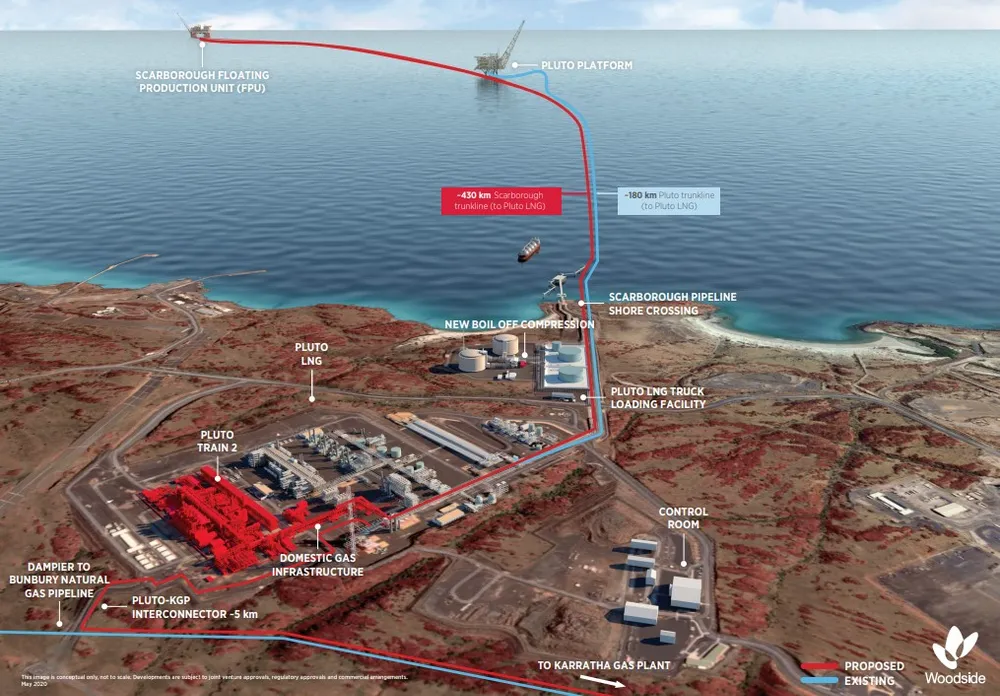
- More Growth to Come: Scarborough 8MT per annum LNG is 98% complete on time, and on budget (see below with costs contained by utilising existing Pluto infrastructure), first cargoes slated for late 2026; Trion in the Gulf of Mexico is 64% complete, with first oil in 2028; and Louisiana LNG is 28% complete, with first LNG targeted in 2029.
- Balance Sheet: Woodside maintains a strong balance sheet, with a 20% gearing ratio. This is very impressive and reflects the company reducing project risk and capex spend by selling down equity stakes in projects to offtake partners.
- Green Energy Projects under the Axe: the new WDS CEO is revisiting the green energy project plans installed by her predecessor; this will see a strategic review of the newly constructed Texas green ammonia plant and abandoning the goal of investing US$5 billion in new energy projects by 2030. With many of these projects having dubious economics, we welcome this greater focus on shareholder returns.
- Dividends: The interim dividend of US$0.57 was ahead of expectations and up +8% on last year.
- Guidance: WDS guided that they expect to produce 172-186 million barrels of oil in 2026, with profits likely higher in the second half. Hedging and contractual pricing lags saw WDS receive only US$74/boe, significantly below spot prices. Since March, oil has averaged US$86/bl, if this is maintained, WDS will see a profit after tax uplift of US$600M in the second half to US$1.9 billion.
Portfolio Strategy: WDS is the Portfolio’s sole energy producer and is the most conservative and well-managed Australian oil company with no exposure to the problematic and politically charged East Coast gas market. WDS has the lowest production cost and gearing, which is a crucial position for an energy company, given that market conditions can change abruptly. WDS trades on a very undemanding PE of 14x with a 5% fully franked yield.
Woodside finished up -1% to $33.00
Scarborough LNG using existing Pluto infrastructure to keep costs down.