Arena REIT (ARF): The listed childcare and medical centre owner reported full-year results on Friday morning, following an update last week about one of its tenants, Edge Early Learning, defaulting on its August rent payment. The HNW Income Portfolio has a 3% weight to ARF.
Key Points:
- Profits Up: Net profit increased by +8% to $79 million, driven primarily by a 10% increase in rents collected and completion of developments and acquisitions. Outside of Edge, ARF continues to have 100% occupancy and an average weighted lease term of 18 years, by far the best in the entire LPT sector, with less than 1% of leases expiring in this decade.
- Dividends Up: ARF announced a distribution of 19.25 cents per security, representing an increase of 6% on last year. Unlike office or retail landlords, ARF benefits from “triple net leases,” which hold tenants responsible for the building’s insurance, taxes, utilities, and all capital expenditures.
- Strong Balance Sheet: ARF’s gearing ratio stands at 25%, with 93% of the debt hedged over the next three years. ARF remains conservatively geared and is a long way from meeting its loan covenants, which require a gearing ratio of no more than 50% and interest coverage of 2 times (currently 5 times).
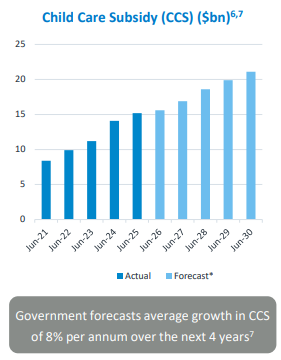
- Regulatory Beneficiary: Despite Edge’s default, the government does not want to see childcare centres fail. Over the last year, the government has introduced a 3-day guarantee from the start of 2026 that will allow all families to be eligible for at least 72 hours of subsidised early learning childcare per fortnight (3 days per week), providing 100,000 families access to childcare. (See Below).
- What to do with Edge: Edge is one of ARF’s smaller tenants and, under private equity ownership, has clearly both mismanaged their centres and taken on too much debt – a lethal combination. ARF have already signed leases on two brand new Edge properties with other operators and will look to reassign leases on the remaining properties if Edge does not pay their back rent by the 25th August. Post our call with management today, we have a degree of confidence that ARF will manage the situation to shareholders’ advantage.
- Outlook: ARF management announced a FY27 distribution guidance of at least 18 cents per security, representing a distribution yield of 7.2%, with a risk to a higher distribution if ARF is able to collect rent from the current Edge centres from either Edge or a new tenant.
Portfolio Strategy: ARF is a well-managed company that owns 284 childcare and medical centres across Australia, which are exposed to tenants offering non-discretionary services such as childcare and healthcare, both of which enjoy bipartisan support. ARF pays a solid, growing yield directly linked to inflation and is paid quarterly, providing regular cash flow to our investors. The next major set of lease expiries is in 2037 and 2038, so we have few near- and medium-term concerns. ARF trades on a 7.2% yield paid quarterly.
ARF finished up +3% to $2.49. The initial fall in the share price last Monday wiped out the equivalent of 21 years of Edges’ rent from ARF’s market cap, which made little sense to us.