Commonwealth Bank (CBA) reported its full-year results for 2026, which showed that the underlying business was operating solidly as Australia’s largest bank. Due to the breadth of its lending activities, which touch every sector, CBA is closely watched for a read on the broader Australian economy’s health. HNW Growth has a 7% weight to CBA (index weight 10.4%).
Key Points:
- Record Profits: CBA reported profits increased by +7% to $11 billion, following market share gains across retail and business banking. For the first time in 15 years, all four of CBA’s core businesses grew at or above average system growth as CBA steps up its loan pricing across its portfolio. (See Below)
- Net Interest Margin Up: This increased loan volume did not see CBA lower its margins, with CBA’s net interest margin increasing to 2.05% from 2.04%. This was achieved with increased volumes for both home deposits and business lending, offsetting increased mortgage competition.
- Bad Debt Remains Low: Bad debts sat at 0.08% of Gross Loans, Well Below the Long-Running Average of 0.3%. While unemployment remains low, Atlas expects banks’ loan losses will remain low, particularly when much of the more “exciting” high-yield lending to developers is not on bank balance sheets but rather with Private Credit Funds.
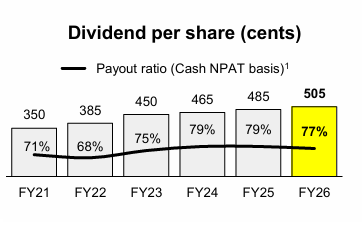
- Dividend up: CBA announced a full-year fully franked dividend of $5.05 (74% payout), representing a 4% increase on last year. CBA also announced that it would fully neutralise its Dividend Reinvestment Plan (DRP), meaning that current investors are not being diluted, as CBA will buy roughly $450 million worth of CBA shares before distributing them to investors.
- Capital High: Tier 1 capital high at 12.0%, which is over $9 billion higher than the capital requirement for the bank. This provides CBA ample runway for continued expansion into business and institutional banking whilst supporting continued shareholder returns.
- Outlook: No direct profit guidance was provided, but management discussed that the three interest rate increases in 2026 are having their desired effect, with economic growth slowing, driven by weaker household spending. CBA does not expect to be impacted by the slowdown, with unemployment still sitting near all-time lows and 85% of customers in advance of their payments.
Portfolio Strategy: Following this result, Atlas maintains its view that CBA is the best bank in Australia; however, it is currently trading at a very expensive multiple, which has led Atlas to position CBA as a portfolio underweight. What to do with the banks in 2026 and beyond has been a key question for investors, as global investors started buying instead of shorting the Australian banks. Atlas have been slower than most fund managers to reduce our banks’ exposure due to the combination of buy-backs and lower-for-longer bad debts.
CBA finished down -1% to $172.72, matching the market on a weaker day. The market was sweating on this result and if CBA’s results disappointed it would have set the tone for the rest of the season.