Deterra Royalties (DRR): Australia’s only iron ore and lithium royalty trust and the most boring miner on the ASX has released its full-year 2026 results, which were quite pleasing. For DRR, there is minimal scope for surprises on results day, as revenue and production data were pre-released. The company is a royalty trust that passes through payments to BHP with a 95% profit margin. The HNW Portfolio holds a 2.5% weight to DRR.
Key Points:
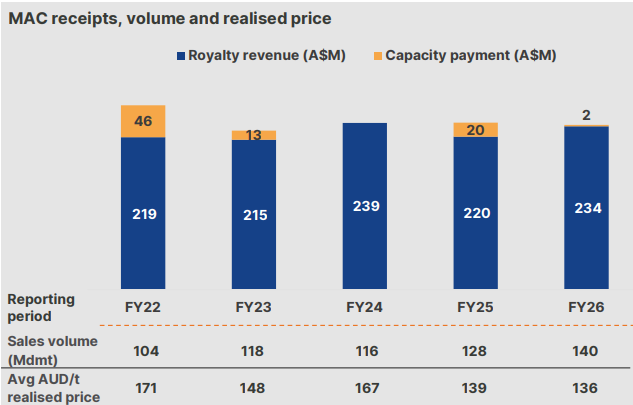
- Record Profits: Deterra posted profits up 5% to $164 million, driven by a 9% increase in iron ore sales volumes that was partly offset by a lower iron ore price. DRR only saw a $2 million capacity payment over the year, with BHP’s Mining Area C approaching its nameplate capacity.
- Strong Balance Sheet: DRR has improved its balance sheet over the last year following the sale of the gold royalties for $108 million, with net debt sitting comfortably at $132 million.
- Dividend Up: Deterra announced a full-year fully franked dividend of 23.2 cents per share, representing a 75% payout ratio of earnings and a +5% increase on last year.
- Outlook: Although management did not point to specific guidance over the next year or months, they did state that they would be disappointed if they did not acquire one or two new royalty streams over the next 12-18 months. Looking further ahead, the DRR’s lithium royalty stream in Nevada is expected to be completed in 2027, largely funded by the US Department of Energy, with DRR receiving a royalty stream of 1.05% of gross revenue from the 160,000-tonne-per-annum project. At current prices, this will result in DRR receiving an additional $50 million per annum in profits.
Portfolio Strategy: DRR is a royalty trust that owns an income stream based on 1.23% of the revenue BHP receives from iron ore mined in the Mining Area C iron ore tenements and eventually from lithium in the United States. As a royalty trust, DRR is not responsible for operating the mine, raising wages, capital expenditures, or cleanup costs, which is an attractive proposition. DRR’s assets are low-cost, and diversifying royalty revenue streams will reduce volatility in the medium term. DRR trades on a fully franked yield of 6%.
DRR finished up 3% to $4.35