Region Group (RGN): This morning, Australia’s largest convenience mall landlord, RGN, released its full-year results for 2026, which were largely in line with expectations. The HNW Income Portfolio has a 2% weight to RGN.
Key Points:
- Profits Up: Regions Funds from Operations (FFO) was up 3% on last year to $185 million, with increases in long-leased property rents being slightly offset by interest and corporate expenses.
- Distributions Up: Distributions were up 3% on last year to 14.1 cents per share
- Operational Performance: RGN continues to manage its portfolio well, with occupancy at 98% and a strong average lease term of 4.6 years. Tenant sales in the centres remained strong, with sales increasing by 3.1%, led by Supermarkets (+4.1%), Medical and Beauty (+2.5%) and Discount Department Stores (+1.7%). Currently, 58% of supermarket anchors pay turnover rent in addition to base rent, with a further 15% close to paying turnover rent as well.
- Balance Sheet: Interest rate hikes are no problem for RGN as gearing is currently at 34%, at the lower end of the target range of 30-40%, and 100% of its debt is either hedged or at a fixed rate. RGN currently has an average cost of debt of 4.5% and an average debt maturity of 3.8 years, with no debt maturing until 2028.
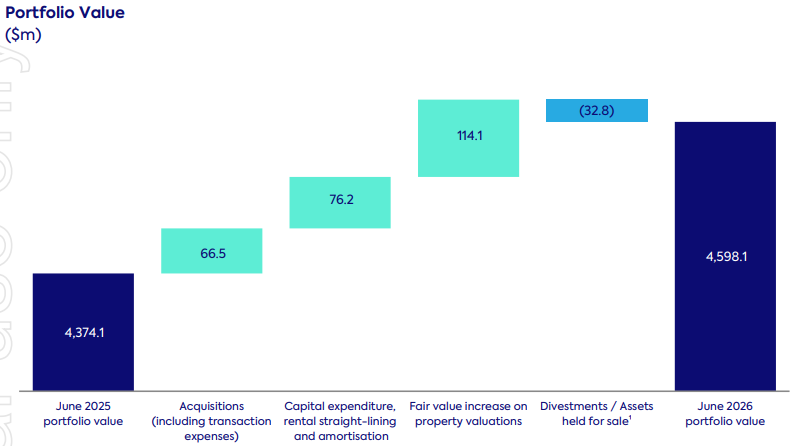
- Valuation: NTA increased by 10 cents per share to $2.57, driven by increased valuation of investment properties in combination with an on-market share buyback reducing outstanding shares. (See Below)
- Outlook: RGN management provided guidance for 2026 of Funds from Operations of 16.5 cents per share, representing an increase of 3% on this year, bolstered by the resilient nature of non-discretionary spending and rent growth. The target distribution payout ratio is 90% of FFO
Portfolio Strategy: RGN offers the portfolio exposure to non-discretionary retailing via a diversified portfolio of neighbourhood shopping centres typically anchored by a Woolworths or Coles supermarket with an accompanying Dan Murphy’s or BWS. Unlike better-known retail landlords such as Scentre or Stockland, RGN’s tenants are not particularly exposed to the impact of online sales or the Coronavirus impacting tourism, with consumer staples and alcohol, as well as medical and personal services such as haircuts, not easily delivered online and bought almost entirely by local Australian residents. Long leases to quality tenants such as Woolworths, Coles and Aldi give a high degree of confidence that RGN can maintain and grow its distributions over time. RGN currently trades on a 6.5% distribution yield and at a 11% discount to NTA.
RGN finished down -2% to $2.31