Westpac Banking Corporation (WBC) released its half-year results for 2026, largely in line with market expectations following last week’s earnings preview. WBC is the last of the big four banks to report, with Macquarie to provide its results on Friday. The HNW Core Portfolio has a 7% weight to Westpac.
Key Points:
- Profits Up: Net profit increased by 1% to $3.4 billion with increases in interest income offset by increased spending on technology, including the WBC UNITE program, which is expected to bring $160 million in savings per year in the coming years.
- Low Bad Debts: Bad debts are nowhere to be seen in Westpac’s results, with a mere 0.1% of loans currently being impaired. Atlas continues to believe that the “riskier” loans now sit with private credit funds rather than with banks, which must hold capital against them.
- Business Banking: Westpac stepped up its lending to business and institutions over the year, with lending increasing by 13% and institutional lending up 23%, with a focus on Agriculture, Health and Professional Services rather than the riskier industries such as construction and property development.
- Strong Balance Sheet: Westpac currently has a capital ratio of 12.4%, well above its long-term target range of 11.25%. This provides Westpac with ample runway for continued expansion into business and institutional banking.
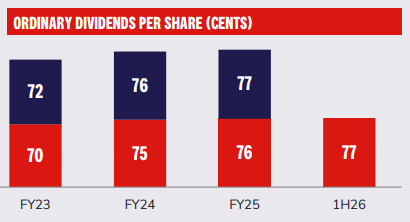
- Show me the Money: WBC announced a 1% dividend increase to 77 cents per share fully franked (See Below), representing a payout ratio of 76% of profits. The dividend reinvestment plan will be neutralised by buying back shares.
- Guidance: Westpac management did not provide explicit guidance for next year due to fast-evolving capital funding costs, but did state that they expect to benefit from further increases in the Australian cash rate.
- Why is the Stock down? The market remains cautious about Westpac’s growth ambitions in the current macroeconomic environment, particularly in light of NAB showing higher bad debts yesterday.
CEP Strategy: This was a solid result from Westpac, with the business travelling well. We own WBC in the portfolio due to its heavy exposure to mortgages, which account for 68% of its loan book. Through the cycle, mortgages have historically had much lower bad debt charges than business lending due to Australia’s home loan recourse lending and higher margins. We expect loan losses to remain low or slightly increase going forward, and we are likely to see expanding margins from the RBA tightening interest rates. We remain happy holders of the bank, which trades on a PE of 17x with a 4% dividend yield.
WBC finished down 2% to $37.63, but has been a solid citizen in the portfolio, returning 21% over the past year, ahead of the ASX200 return on 10%.