This morning, JB HI-FI (JBH), the local electronics and home appliance retailer, delivered its full-year results, which highlighted that Australian consumers are still spending, but more during promotional periods. The HNW Core Portfolio has a 2% weight to JB Hi-Fi.
Key Points:
- Profits Up: JB Hi-Fi reported earnings growth of 6% to $490 million, driven by increased sales for AI-enhanced computers and mobile phones at JB Hi-Fi and increased sales for coffee machines and robot vacuum cleaners at the Good Guys.
- Troubles getting Stock: Due to the high demand for AI-enhanced computing in data centres, JB Hi-Fi struggled to secure supply of many computers and gaming devices over the half, which weighed on the strong sales that we saw in the first half. During the call, management did highlight that they have seen the problem begin to fade over the month of July and expect it to largely be resolved before Black Friday sales.
- No Debt: JBH continues to have one of the best balance sheets on the ASX, with a net positive cash position of $200 million. Conversely, JBH’s competitor, Harvey Norman, spends over $120 million per annum to service its $ 1B-plus debt pile, which gives JBH a cost advantage along with the carefully curated perception of the cheapest electrical goods retailer in Australia.
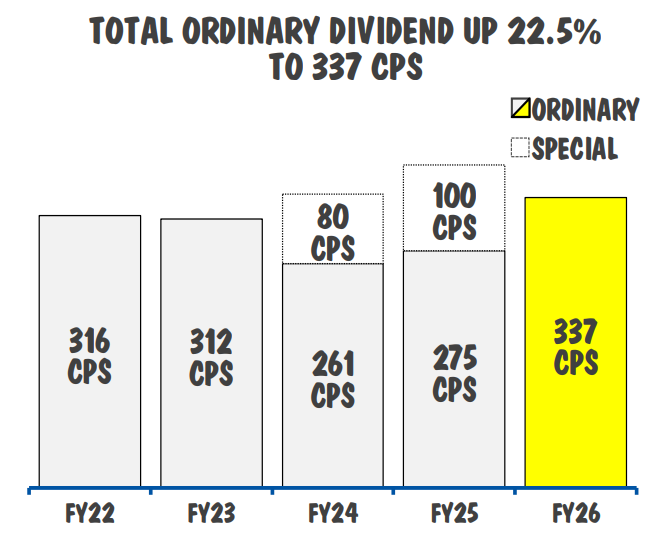
- Dividends Up Strongly: Interim dividend up +23% to $3.37, driven by a rework of the dividend policy this year, which has seen the payout ratio increased from 60% of profit to a range of 70-80% of profits. Atlas sees this as a welcome way to return cash to shareholders through fully franked dividends.
- Outlook: JB Hi-Fi management provided a weaker trading update, showing that JB Hi-Fi Australia’s sales fell by 1% in July 2026. Whilst this is disappointing, July is not a very good read-through for JB Hi-Fi, with no promotional periods in the month. Atlas is looking forward to the Black Friday sales data, which we expect to show an increase in sales. We were pleased to see former CEO Terry Smart has been appointed to the board, bringing over 22 years of experience at JB Hi-Fi, with 8 of those being as CEO. A great outcome for JBH and its shareholders.
- Why is the stock down? The stock is down following a 0.5% decline in sales in July, but JB Hi-Fi is currently cycling some tough comps from July 2025, when the launch of the Nintendo Switch 2 and the Samsung Fold phone (see below) was pushed out to August 2026, along with the company facing issues getting stock from suppliers.
JBH finished down -12% to $71.65. This looks like an over-reaction to a small and explainable decline in one month’s sales.
Portfolio Strategy: JBH’s business model is based on low prices, low overheads, and high volumes. Regarding the cost of doing business (rent, administration and sales staff costs), divided by sales, JBH is one of the most efficient retailers globally, a remarkable outcome given Australia’s high wages and is Australia’s largest electrical retailer and the world’s seventh-largest electrical retailer. More importantly, JBH has consistently recognised declining (CDs) and growing (fitness devices) categories and switched inventory to take advantage of these shifts; the expansion into Home and white goods has proved very successful. JBH looks cheap for a premium retailer trading at a PE of 18x and offering a 4.5% yield after a share price pullback.