Charter Hall Retail (CQR): This morning, the supermarket and service station landlord reported their full-year results for 2026, which were largely in line with market expectations, albeit with a brighter outlook. Though generally, there should be minimal excitement on results day for this very boring and stable supermarket trust. HNW Income has a 3.5% weighting to CQR.
Key Points:
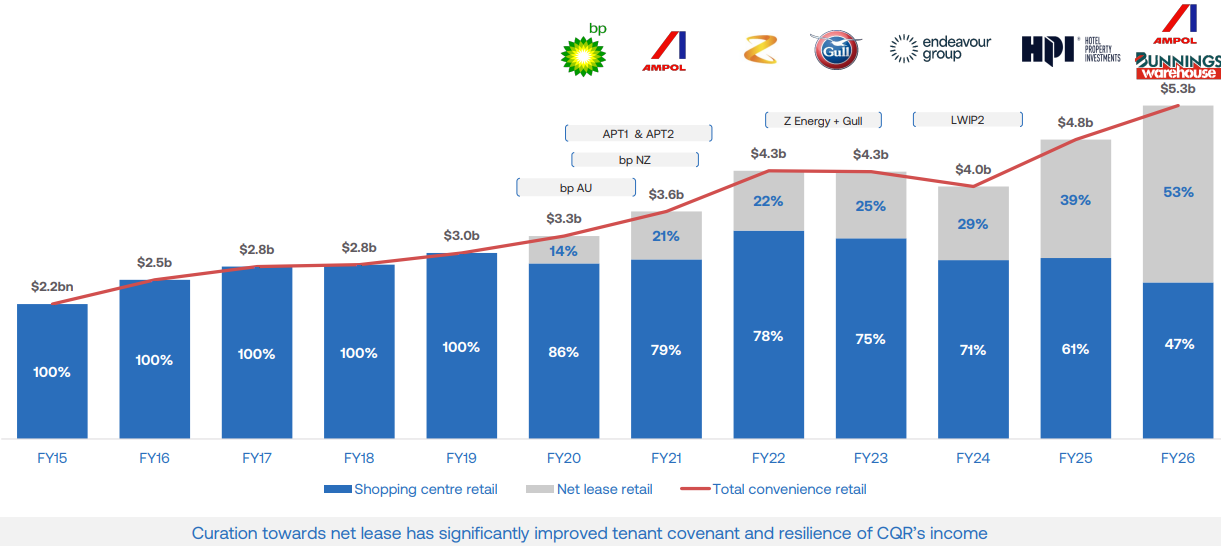
- Earnings Up: CQR reported a 4% increase in profits to $153M, driven by an 11% increase in property income, which was partly offset by higher interest repayments. Over the half, CQR has been busy in the market, divesting $400 million in assets and acquiring $500 million in new assets with a focus on service station sites in Queensland. This has moved CQR to a near 50-50 split between shopping centres and convenience retail sites. (See Below)
- Balance Sheet: Following the transactions, gearing currently sits at 31%, with an average cost of debt of 5.0%, with an average debt maturity of 4 years. The lower cost of debt follows a $1.6 billion refinance during the half that lowered the interest rate by 0.4%.
- Distribution Up: CQR reported a full-year distribution of 25.5 cents per share, representing a 3.3% increase on last year’s distribution.
- Valuation Up: NTA increased by 39 cents or 8.5% to $5.03, following convenience retail valuation growth driven by inflation-linked rental income and strong asset transactions.
- Outlook: CQR management provided guidance for FY27 operating earnings to be 27.3 cents per unit with a distribution of 26.4 cents per unit, representing a 3.5% increase in this year’s distribution and a 6.5% distribution yield. A little ahead of expectations, which is why the share price is up today.
Portfolio Strategy: CQR offers the portfolio exposure to non-discretionary retailing via a diversified portfolio of neighbourhood shopping centres typically anchored by a Woolworths or Coles supermarket, as well as service stations. Long leases linked to CPI to quality tenants such as Woolworths, Coles, Bunnings, Aldi, Ampol and BP give a high degree of confidence that CQR can maintain and grow its distributions over time.
CQR finished up +4.2% to $4.23