Arena REIT (ARF): This afternoon, the listed childcare and medical centre owner reported an update on the Edge Early Learning administration process that was significantly better than we expected. For reference, Edge was a private equity-owned childcare operator that came unstuck earlier in 2026 due to a combination of high debt and operational/compliance issues, which led authorities to order several of its centres in South Australia to temporarily close; ARF was their landlord. The HNW Income Portfolio has a 3% weight in ARF.
Key Points:
- Edge Transactions: ARF announced that its largest tenant, Goodstart Early Learning, would be buying 20 centres’ operations from Edge’s administrators that are owned by ARF. This is on top of the two brand new Edge centres that were about to open and were transferred to another childcare operator in August.
- Still Collecting Rent???: Despite Edge going into administration, Edge’s administrator has still been paying rent on all 27 of their properties. So ARF shareholders have not lost any income so far, not quite what we expected.
- More Sales to Come: The Edge Administrators still have 7 childcare businesses to sell that are owned by ARF, with ARF engaging the administrators and other tenants about potential sales.
- ARF Collateral: Due to ARF still collecting rent from its 27 properties, ARF still has retained $4 million in security deposits or 12 weeks of rent across all the properties if this process falls through.
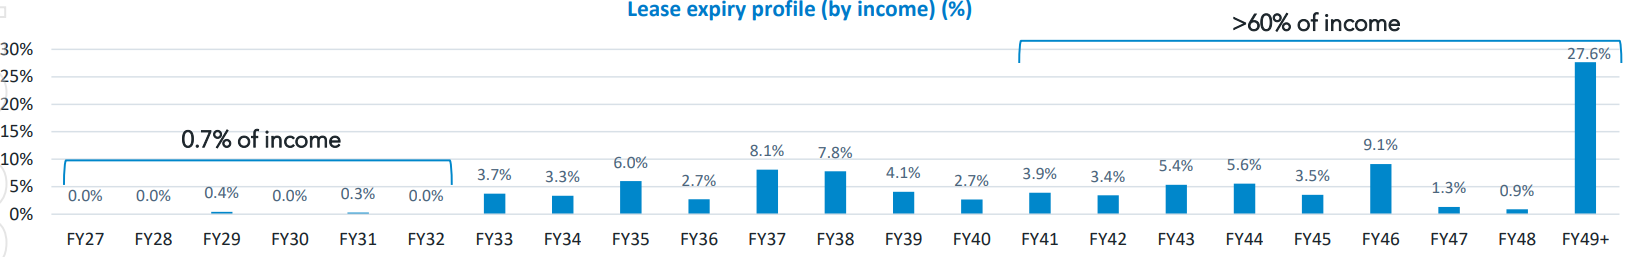
Portfolio Strategy: ARF is a well-managed company that owns 284 childcare and medical centres across Australia, with tenants providing non-discretionary services such as childcare and healthcare, both of which enjoy bipartisan support. ARF pays a solid, growing yield linked to inflation and pays quarterly, providing regular cash flow to our investors. The next major set of lease expiries is in 2037 and 2038, so we have few near- and medium-term concerns. ARF trades on an 8.7% yield paid quarterly.
ARF management has moved surprisingly fast to ameliorate the potential earnings hole from Edge’s demise, which was likely to drag on for months; this reflects the quality of ARF’s portfolio. We would expect ARF to re-rate upwards.
ARF finished up +13% to $2.35, following the update.